By StartBusinessByStatePublisher: Robert SmithResearch process
Maryland’s Family and Medical Leave Insurance (FAMLI) contributions start January 1, 2027. Under the State Plan, businesses with 15 or more employees owe an employer share of 0.45% of covered wages; smaller employers have no required employer share. Both groups still have remittance obligations. The calculator below separates what your business pays from what it withholds from employees.
Reviewed September 18, 2026 · 2027 State Plan rates · Official Maryland sources · Illustrative cost scenarios
Estimate your quarterly Maryland FAMLI contribution
Use the employee count and contribution-subject payroll for the same 2027 quarter. Headcount covers all states; the wage input covers Maryland-qualified employment. This tool does not determine which workers are covered or apply the wage cap for you.
Formula: employee share = subject wages × 0.0045. Required employer share = subject wages × 0.0045 for 15+ employees, otherwise $0. Total remittance adds both shares; choosing to absorb the employee share changes who funds it, not the total. Estimates use aggregate payroll; actual per-employee rounding can differ by cents. Private-plan premiums, payroll administration, replacement staffing and other taxes are excluded. Official 2027 contribution rates.
Why the 15-employee threshold matters
A smaller employer is not outside the program. It can withhold the required 0.45% from employees and remit it, leaving no required employer-funded contribution. At 15 employees, the employer’s own 0.45% share applies to covered wages across the business, not only to the fifteenth employee.
The regulations count employees paid any wages during the quarter, including people outside Maryland. For 2027, the determination is quarterly. It is not a snapshot of today’s staffing, a full-time-equivalent calculation or a count of Maryland workers alone. Independent contractors do not count as employees. COMAR 09.42.02.06 and the contribution rules explain the calculation.
When someone leaves and a replacement joins, do not assume the headcount stayed unchanged for this purpose: both may have received wages during that quarter. Starting in 2028, the program generally uses the previous four quarters to determine employer size; this calculator deliberately models the 2027 quarterly rule.
Modeled annual cost at $40,000 per employee
These are hypothetical budgets, not observed industry wages or forecasts. Each employee is assumed to have $40,000 in annual Maryland contribution-subject wages, earned evenly, with the same employer-size category throughout 2027. Employees fund the full permitted employee share.
| Employees | Annual subject payroll | Required employer cost | Employee withholding | Total remitted |
|---|---|---|---|---|
| 1 | $40,000 | $0 | $180 | $180 |
| 5 | $200,000 | $0 | $900 | $900 |
| 10 | $400,000 | $0 | $1,800 | $1,800 |
| 14 | $560,000 | $0 | $2,520 | $2,520 |
| 15 | $600,000 | $2,700 | $2,700 | $5,400 |
| 20 | $800,000 | $3,600 | $3,600 | $7,200 |
| 25 | $1,000,000 | $4,500 | $4,500 | $9,000 |
| 50 | $2,000,000 | $9,000 | $9,000 | $18,000 |
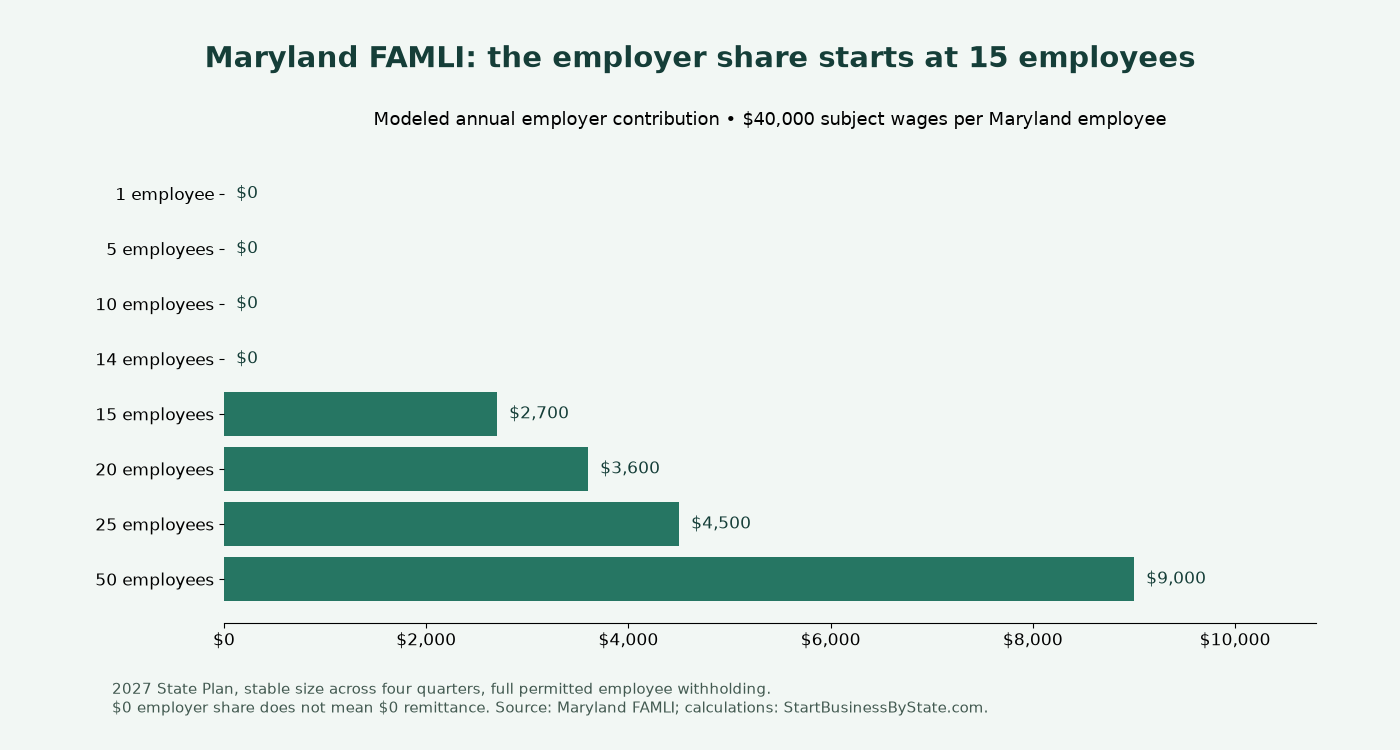
The 14-to-15 illustration: employer cost rises from $0 to $2,700 a year under these assumptions. That is $675 per quarter, not merely the new employee’s $180 annual employer share. The change combines hiring one employee with becoming responsible for the employer share on the whole covered payroll. If the threshold is crossed for only one quarter, use that quarter’s wages instead of applying the annual illustration.
Contributions in 2027, benefits in 2028
- Before withholding begins: notify employees at least one pay period ahead of the deduction.
- January 1, 2027: contributions begin on applicable wages.
- April 30, 2027: the first quarterly report and contribution payment are due, covering January–March.
- July 2027: the general employee-notice requirement starts, ahead of benefit availability.
- January 1, 2028: benefits become available under the current program schedule.
Later quarterly filings are due at the end of the month following the quarter; Maryland provides a next-business-day payment rule for weekends and legal holidays. The payment is not postponed until employees can claim benefits. Sources: quarterly reporting guidance, employer notice requirements and program launch schedule.
What a service business should do before payroll starts
Have an Authorized Officer complete employer registration. Maryland allows one registration per EIN, and a payroll provider cannot perform that initial registration for you. Afterward, you can authorize a third-party agent to help with reporting and payment. Gather your EIN, legal business name, NAICS code and resident-agent information before starting. Use Maryland’s registration instructions.
Then ask payroll to confirm work localization, employee counting, the applicable wage cap and withholding notices. An ordinary missed deduction generally becomes the employer’s responsibility; it cannot simply be recovered from a later paycheck. The rules include a narrow insufficient-paycheck exception. Treat payroll setup as a separate task from making the first quarterly payment.
If you are considering a private plan, check the FAMLI Division’s approval and declaration-of-intent process before assuming you can avoid State Plan contributions. Private plans still carry reporting duties and their own costs. This calculator does not quote private coverage. Review the official private-plan requirements.
FAMLI is not general liability or workers’ compensation coverage. Cleaning employers budgeting those separate risks can use our Maryland cleaning-business insurance guide. The commercial-contract cash guide helps place payroll and remittance timing alongside customer collections.
Sources, formulas and downloadable worksheets
We checked Maryland’s official FAMLI guidance, COMAR and 2025 Chapter 363 (HB 102), with enactment cross-checked through LegiScan. This is an upcoming implementation guide, not a claim that the program was newly enacted in 2026. Regulations were finalized in March 2026. The model uses the published 2027 rate and should be rechecked before payroll launch or use for a later year.
Original calculations multiply hypothetical contribution-subject wages by the applicable shares. They do not estimate employment, industry wage averages, take-home pay after all taxes or realized business costs. Annual examples assume four identical quarters; the interactive tool calculates one quarter. Inputs stay in the calculator and are not submitted by it. No Social Security numbers or employee names are needed.
Writers may reuse the original chart and calculations with attribution and a link to this page. Retain the 2027 rate, $40,000 wage assumption and distinction between employer cost and total remittance.
Common questions
Does a business with fewer than 15 employees pay nothing?
It has no required employer share, but still must handle the applicable employee contributions and reporting. If it chooses to fund employees’ shares, that becomes a business expense. Administration and other payroll obligations remain separate.
Should I enter all company wages in the calculator?
No. Use all-state headcount for the size test, but only wages subject to Maryland FAMLI for the payroll input. Apply the annual cap separately to each employee before totaling the quarter’s subject wages.
Is this the same as paid sick leave?
No. FAMLI is a separate family and medical leave insurance program. This estimate does not replace a review of sick-leave obligations or other payroll costs.
Can a self-employed owner use this as a personal contribution quote?
No. This is an employer State Plan model. Maryland says details about its optional self-employed program will be available in 2028; do not treat that as current enrollment or use employee assumptions for owner-only coverage.