ABI/Epiq · Judicial Conference · SBA 7(a) FOIA · As of Sep 18, 2026 · Proposed / not current law (H.R.7730 / S.3977 pending)
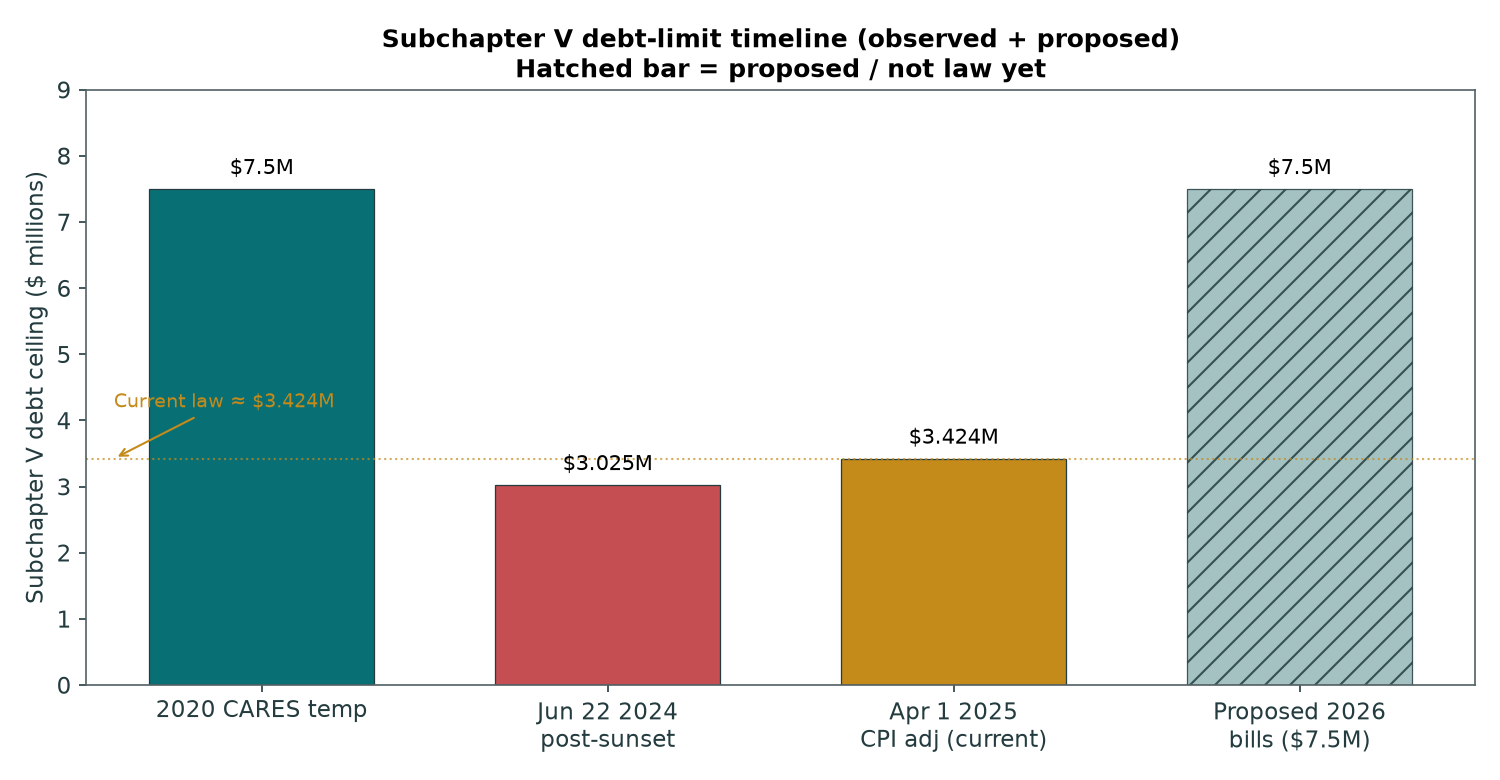
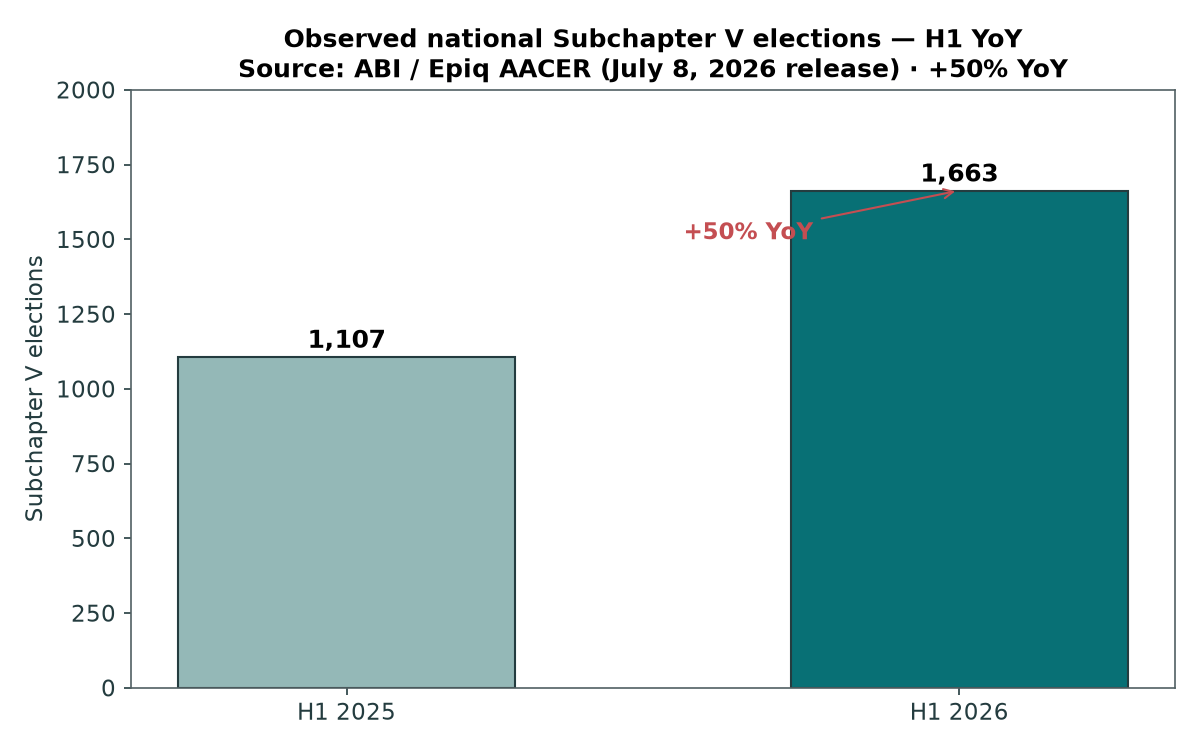
Congress has moved to restore a permanent $7.5 million Subchapter V debt ceiling — but it is not law yet. Under current law, the operative small-business / Subchapter V debt limit is $3,424,000 (Judicial Conference CPI adjustment effective April 1, 2025, after the CARES/BTATCA $7.5 million temporary ceiling expired June 21, 2024). The Senate passed S.3977 on August 3, 2026; the House passed companion H.R.7730 in mid-September; as of September 17–18 both chambers still need to approve identical final text before enrollment and a presidential signature. Meanwhile, ABI/Epiq report 1,663 Subchapter V elections in H1 2026 — +50% year-over-year. This page leads with the statutory debt-limit change; it is not a redo of survival rates and is not legal advice.
Three findings reporters can use
- Observed (current law): After BTATCA’s $7.5 million Subchapter V debt-limit provision sunset on June 21, 2024, eligibility reverted to the small-business-debtor definition. The Judicial Conference’s April 1, 2025 adjustment set 11 U.S.C. §101(51D) at $3,424,000 (from $3,024,725). FR Doc. 2025-02207 notes there is no standalone dollar currently printed in §1182(1).
- Observed (legislative status — not enacted): S.3977 passed the Senate by unanimous consent (Aug 3, 2026). H.R.7730 passed the House and was received in the Senate (Sep 17, 2026). Both propose restoring a $7,500,000 Subchapter V ceiling. ABI and Reuters state the chambers still need matching final text before the bill can be enrolled and signed. Label: proposed / pending — not “restored” as law.
- Observed national filings vs loan-size proxy: ABI/Epiq: 1,663 Subchapter V elections in H1 2026 vs 1,107 in H1 2025 (+50%). ABI does not publish site-NAICS Subchapter V counts in the cited release — we do not invent industry filing shares. Separately, among site-industry SBA 7(a) approvals FY2021–FY2025 (FOIA as of 2026-06-30), 319 of 21,658 (1.47% of count; 16.7% of dollars) had GrossApproval ≥ $3.424M — a loan-size proxy near the current ceiling neighborhood, not a debtor list.
Distinct from survival / charge-off magnets. Companion pages cover business survival rates by state, SBA loan statistics, and SBA $3M GrossApproval size bands. This study is about the Subchapter V statutory ceiling.
Bill status verified (as of 2026-09-18 ET)
| Instrument | Chamber action | Proposed Sub V ceiling | Primary link |
|---|---|---|---|
| S.3977 — Bankruptcy Threshold Adjustment Act of 2026 | Passed Senate without amendment by Unanimous Consent (2026-08-03); Received in House / Held at the desk (2026-08-10) | $7,500,000 | Congress.gov · Engrossed text |
| H.R.7730 — Bankruptcy Threshold Adjustment Act | Passed House (mid-Sep 2026); Latest Action: Senate — 2026-09-17 Received in the Senate | $7,500,000 | Congress.gov · Engrossed text |
| Reconciliation / enrollment | Substantive provisions described as nearly identical; short titles differ. Identical final text + presidential signature still required (ABI / Reuters / ABF Journal). | — | Reuters 2026-09-17 |
Observed. We verified chamber status on Congress.gov HTML trackers on 2026-09-18. We do not claim the President has signed a public law restoring the ceiling.
Current vs proposed debt limits
| Milestone | Ceiling | Authority |
|---|---|---|
| CARES / BTATCA temporary expansion | $7,500,000 | CARES Act; BTATCA (Pub. L. 117-151) — sunset June 21, 2024 |
| Day after sunset (Jun 22, 2024) | $3,024,725 | Reversion to inflation-adjusted small-business-debtor limit (court notices; FR footnote) |
| Current law (cases on/after Apr 1, 2025) | $3,424,000 | FR 2025-02207 adjusting §101(51D) |
| Proposed in H.R.7730 / S.3977 | $7,500,000 | Pending identical text + signature — not law yet |
| Gap (proposed − current) | ≈ $4.076 million | Debt capacity that would newly sit under Sub V if the bills are enacted as written |
ABI / Epiq national Subchapter V filing trends
National series only — cite ABI partnership with Epiq AACER. No state×NAICS Subchapter V cross-tab appears in the cited H1 2026 release.
| Period | Metric | Value | YoY |
|---|---|---|---|
| H1 2026 | Subchapter V elections | 1,663 | +50% vs 1,107 |
| June 2026 | Subchapter V elections | 258 | +28% vs 202 |
| H1 2026 | Commercial chapter 11 filings | 4,589 | +28% |
| H1 2026 | All commercial filings | 17,285 | +13% |
| 2023 (ABI via Reuters) | Subchapter V share of chapter 11 | 44% | — |
| Jan 2024 – Aug 2026 (Epiq via Reuters) | Cumulative Subchapter V filings | >6,600 | Monthly +89.9% over span |
Source: ABI — Small Business Filings Increase 50% Year-Over-Year in First Half of 2026 (July 8, 2026).
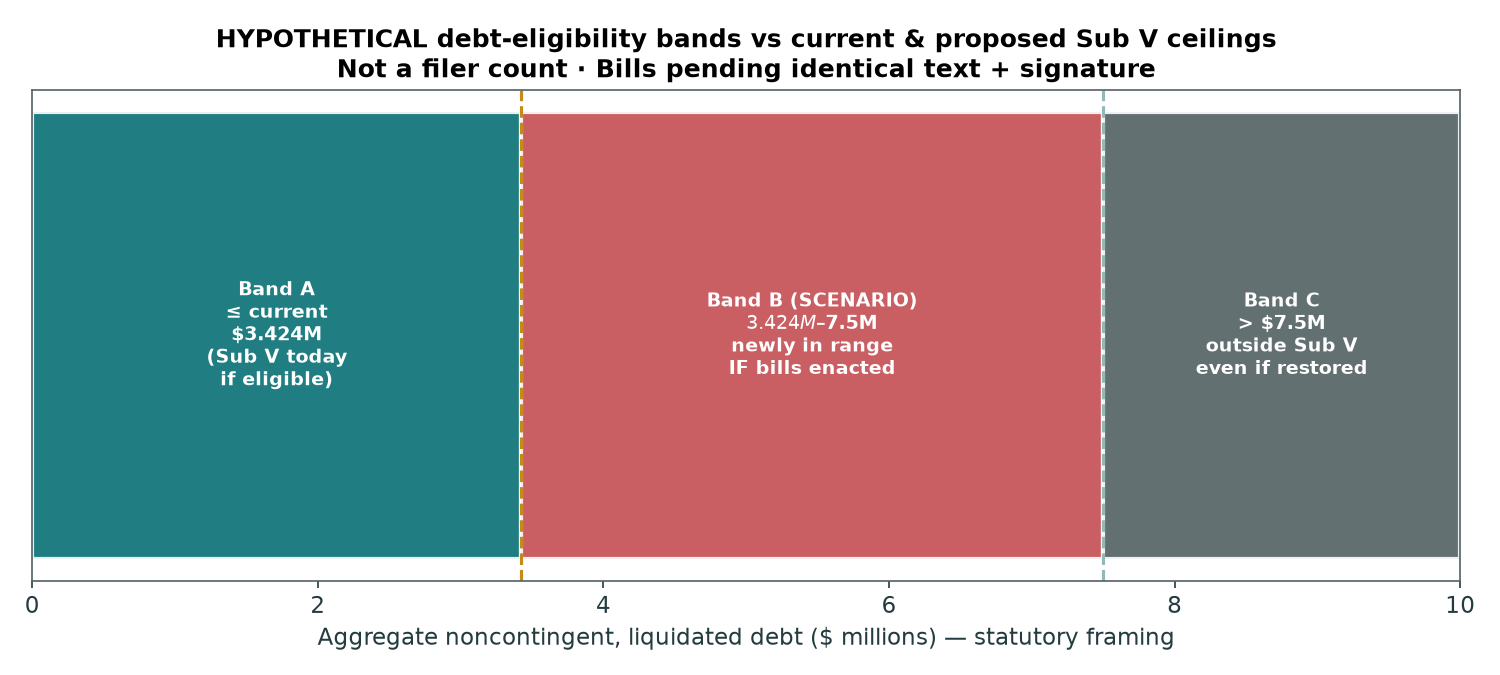
Scenario: who sits near the old vs proposed ceiling?
| Band | Aggregate debt range | Under current law | If $7.5M bills enacted |
|---|---|---|---|
| A | $0 – $3,424,000 | May elect Subchapter V if otherwise eligible | Still within proposed ceiling |
| B | $3,424,001 – $7,500,000 | Generally outside Sub V (traditional chapter 11 if filing) | Newly within proposed permanent Sub V ceiling |
| C | > $7,500,000 | Outside Sub V | Still outside Sub V |
For service-business distress context (not causation): see survival rates by state, sole-prop profit, partnership profit, and ABS credit access.
PROXY: SBA GrossApproval near the current ceiling
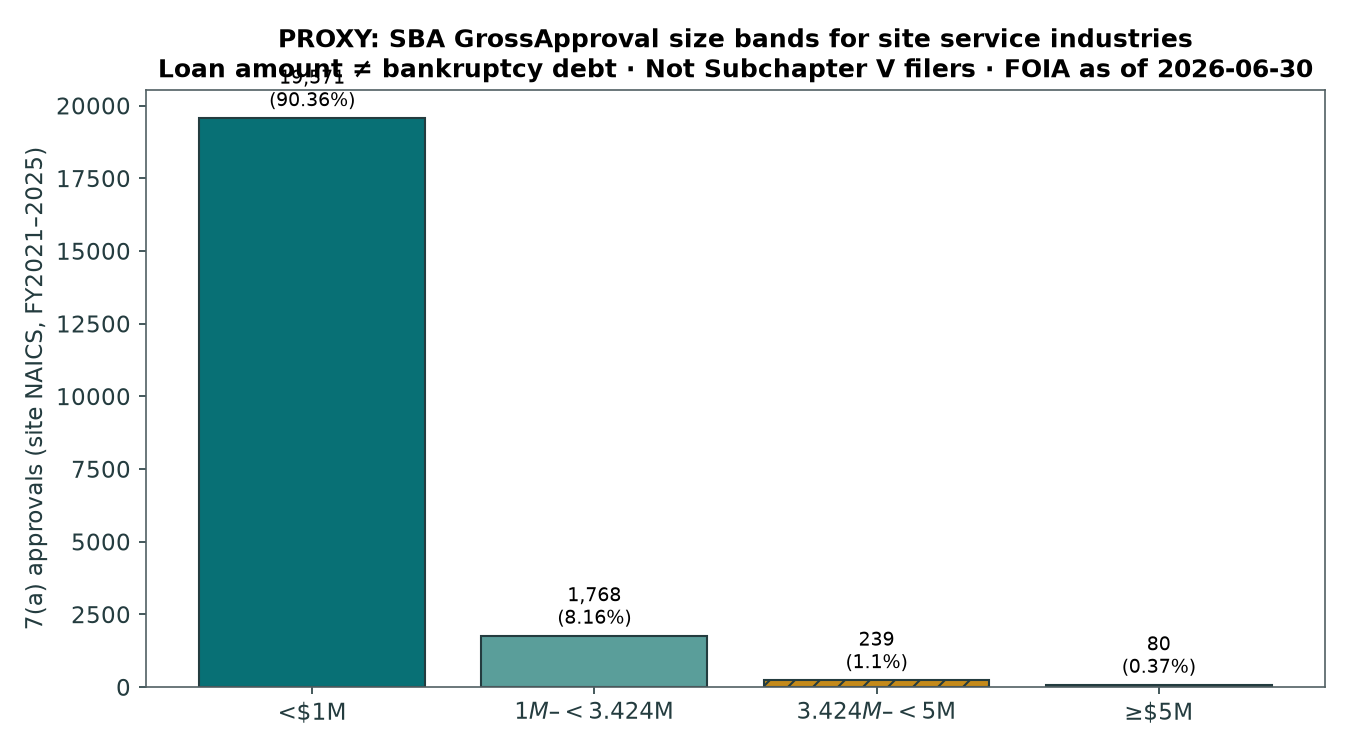
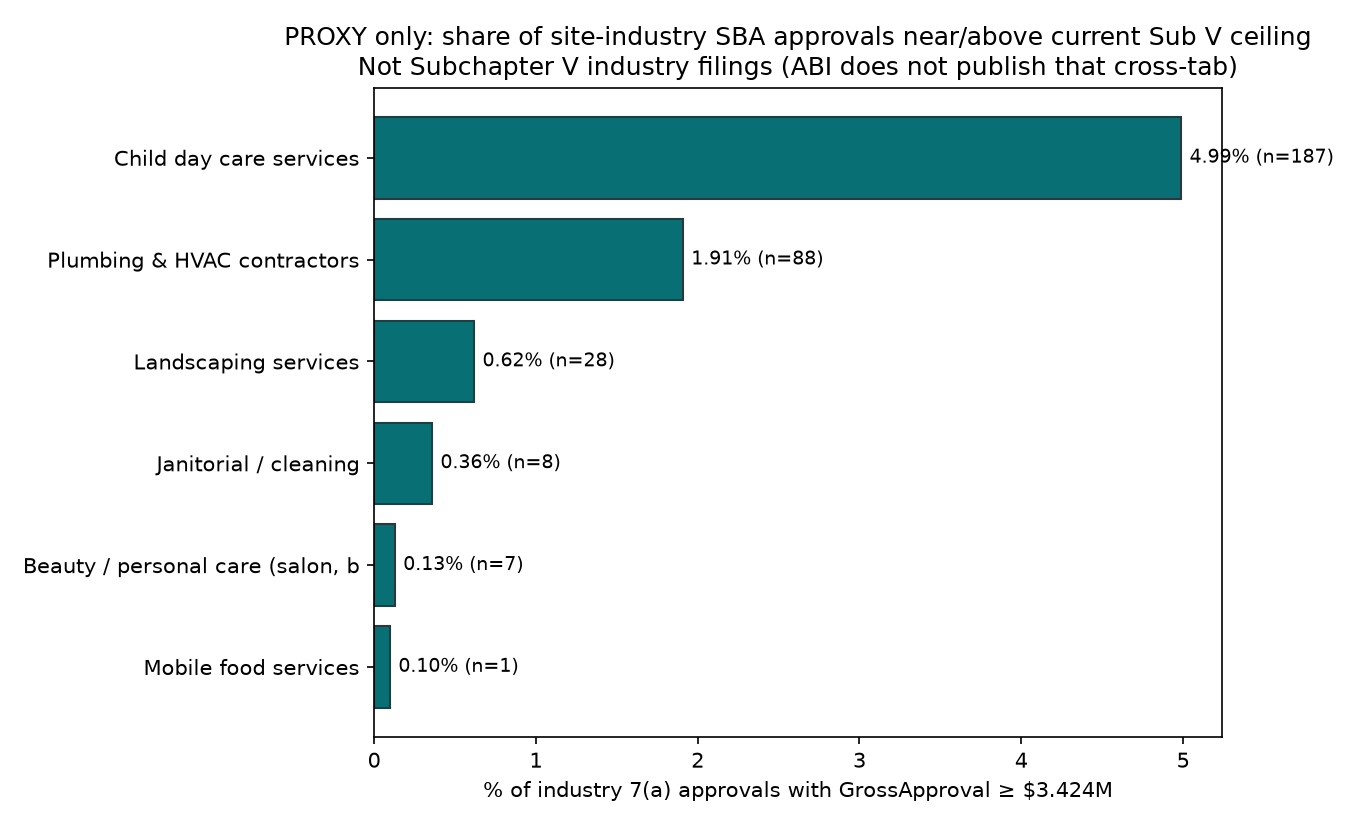
GrossApproval is the approved 7(a) loan amount, not a firm’s aggregate noncontingent, liquidated secured+unsecured debt under the Bankruptcy Code. These rows are not Subchapter V debtors and not industry filing shares. Typical 7(a) caps near $5 million, so FOIA also cannot measure the full $3.424M–$7.5M bankruptcy-debt gap.Universe: site-NAICS 7(a) approvals, complete FY2021–FY2025, FOIA as of 2026-06-30, cancelled excluded. 319 / 21,658 approvals (1.47% of count; 16.68% of dollars) had GrossApproval ≥ $3,424,000.
| GrossApproval band | Approvals | Share of count | $ sum | Share of $ |
|---|---|---|---|---|
| <$1M GrossApproval | 19,571 | 90.36% | $3885.53M | 46.65% |
| $1M–<$3.424M GrossApproval | 1,768 | 8.16% | $3054.36M | 36.67% |
| $3.424M–<$5M GrossApproval | 239 | 1.1% | $989.77M | 11.88% |
| ≥$5M GrossApproval | 80 | 0.37% | $400.00M | 4.8% |
| Industry | All FY21–25 approvals | ≥ $3.424M | Share | $ sum (≥ ceiling) |
|---|---|---|---|---|
| Child day care services | 3,748 | 187 | 4.99% | $832.35M |
| Plumbing & HVAC contractors | 4,607 | 88 | 1.91% | $375.96M |
| Landscaping services | 4,521 | 28 | 0.62% | $111.93M |
| Janitorial / cleaning | 2,243 | 8 | 0.36% | $32.82M |
| Beauty / personal care (salon, barber, nail) | 5,489 | 7 | 0.13% | $31.71M |
| Mobile food services | 1,050 | 1 | 0.1% | $5.00M |
Related size-band companion (SOP Oct 1 context, different threshold): SBA $3M loan size-band by state.
Charts
Related research on StartBusinessByState
- Business survival rates by state — establishment survival context (not bankruptcy elections)
- SBA loan statistics — FOIA volume and charge-off companions
- SBA loans, jobs, and lenders by state
- SBA $3M GrossApproval size-band — SOP Oct 1 size-band proxy
- Sole proprietor profit by state · Partnership profit by state
- Small-business credit access (ABS)
- Business formation statistics
Methodology and limits
Observed vs proposed vs proxy
Observed: Congress.gov bill status; FR 2025-02207 dollar chart for §101(51D); ABI/Epiq national filing totals; engrossed bill text proposing $7,500,000.
Proposed / pending: Restoration of the $7.5M ceiling until identical text is enacted and signed.
Proxy: SBA FOIA GrossApproval bands for site NAICS — credit-size context only.
Primary sources
- H.R.7730 · S.3977
- FR 2025-02207
- ABI H1 2026 small-business filings
- Reuters 2026-09-17
- SBA 7(a) FOIA (as of 2026-06-30)
What this page does / does not claim
- Do not say the $7.5M ceiling is “restored” as current law until a signed public law exists.
- Do not invent Subchapter V filing counts by NAICS or state from ABI national totals.
- GrossApproval ≠ Bankruptcy Code aggregate debt; proxy tables are not debtor lists.
- Not legal, tax, or restructuring advice. Consult counsel for eligibility.
- Distinct from survival-rate and SBA charge-off page intents.